Why Are QR Payments Growing So Fast?
QR payments have moved far beyond being an alternative way to pay. In markets such as Brazil, Argentina, Vietnam and the Philippines, scanning a QR code is their favourite way to pay. For banks, wallets, super apps, PSPs and payment platforms, the important question is not simply why people use QR payments. It is how to enable their customers to pay through local QR networks abroad using their existing banking or wallet app.
1. The infrastructure was already in the customer's pocket
QR payments do not need consumers to change payment behaviour.
The customer already has a smartphone. In many markets, they already have a banking or payment app. The QR code simply becomes the interface between that application and the merchant.
This helps explain why QR payments can grow quickly once the underlying banking and payment infrastructure is in place.
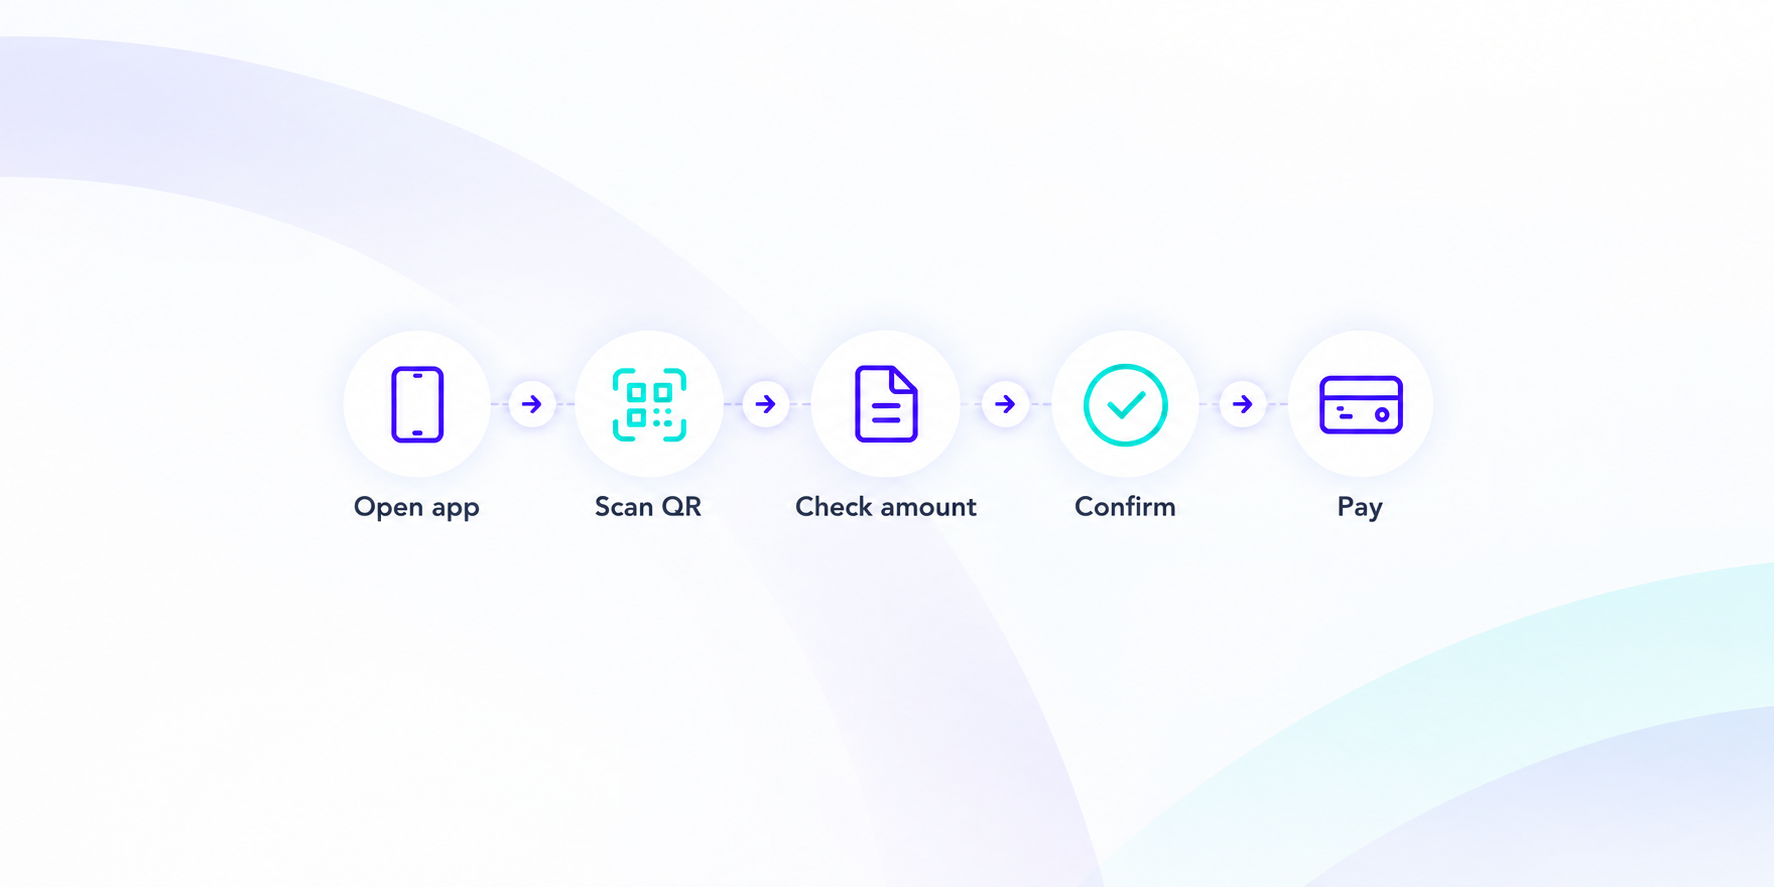
The experience remains simple:
Open app → Scan → Confirm → Pay
The complexity sits behind the screen.
2. One QR can connect multiple participants
The real value of QR emerges when interoperability is possible.
Instead of every bank or wallet creating a closed acceptance environment, a common QR standard can allow customers of different financial institutions to pay participating merchants through the applications they already use.
Argentina provides a clear example.
In August 2026, 117.2 million interoperable payments were initiated through QR codes, up 67.5% year over year. QR accounted for 99.1% of interoperable payments by transfer during the month.
That is no longer an experimental payment channel. It is a payment infrastructure operating at scale.
3. Instant payments changed what sits behind the QR
The QR code itself is only the visible layer.
What made QR considerably more powerful was the development of domestic instant-payment infrastructure capable of moving money quickly between participating institutions.
Brazil is one of the clearest examples.
Pix has reached more than 170 million individual users around 80% of Brazil's population and processed more than 7 billion transactions in May 2026, according to Banco Central do Brasil.
Pix can be initiated in different ways, including QR codes. The important development is not simply widespread QR acceptance. It is the combination of a familiar interface with large-scale instant-payment infrastructure.
For payment businesses, this distinction matters:
The QR starts the payment; the infrastructure behind it makes the payment useful.
4. QR can extend acceptance without changing the customer's app
Another reason for QR growth is that the merchant and the customer do not necessarily need to use the same financial application.
Vietnam illustrates how large this model can become.
By October 2025, nearly 90 million mobile-banking accounts were using banking applications capable of scanning VietQR codes. During the first ten months of 2025, VietQR transaction volume increased by more than 52% year over year, according to NAPAS.
The Philippines has followed the same interoperability principle with QR Ph. The Bangko Sentral ng Pilipinas describes QR Ph as the country's national QR standard, allowing participating banks and non-bank electronic-money issuers to operate within an interoperable QR environment. QR Ph now refers specifically to person-to-merchant payments.
This changes the economics of acceptance.
The objective is no longer to make every customer adopt the merchant's preferred wallet.
It is to let different applications communicate with the same payment ecosystem.
5. Adoption has a domino effect
More participating banks and wallets make a QR ecosystem useful to more consumers.
More consumers make QR acceptance more valuable to merchants.
More merchants make consumers more likely to use QR regularly.
Eventually, scanning is no longer an alternative payment method but a normal payment behaviour.
This is important for businesses entering a new market.
A merchant does not encounter a list of local payment methods. It enters an ecosystem in which consumers already have established ways of paying.
What does this mean for payment businesses?
The growth of QR payments is not really a story about QR codes.
It is a story about local payment infrastructure becoming more connected, interoperable and accessible through the applications consumers already use.
For wallets, Super Apps, banks, neobanks and PSPs, this creates a different international payments challenge.
A user from one market may already have everything needed to initiate a payment: an account, an application and a familiar scan-to-pay experience.
The missing layer is connectivity to the payment ecosystem at the destination.
This is why the next phase of QR payments is increasingly about interoperability across markets.
Domestic QR ecosystems have already shown that different banks, wallets and merchants can participate in a common payment experience.
The next question is whether those ecosystems can work together across borders.
Frequently Asked Questions
Why are QR payments becoming so popular?
QR payments combine a simple consumer interface with increasingly sophisticated banking, wallet and instant-payment infrastructure. In interoperable systems, customers can often pay using an application they already use.
Are QR payments the same as instant payments?
No. A QR code is a way to initiate a payment. An instant-payment system is part of the infrastructure that moves the funds. QR payments can use instant-payment rails, but the two terms are not interchangeable.
Why are interoperable QR payments important?
Interoperability allows customers of different participating banks or payment applications to pay merchants within the same QR ecosystem instead of requiring both sides to use the same provider.
What is the opportunity for banks and PSPs?
As QR ecosystems expand, banks, wallets and PSPs can give their users access to additional local payment environments without asking them to change the payment experience they already know.
You may be interested in: